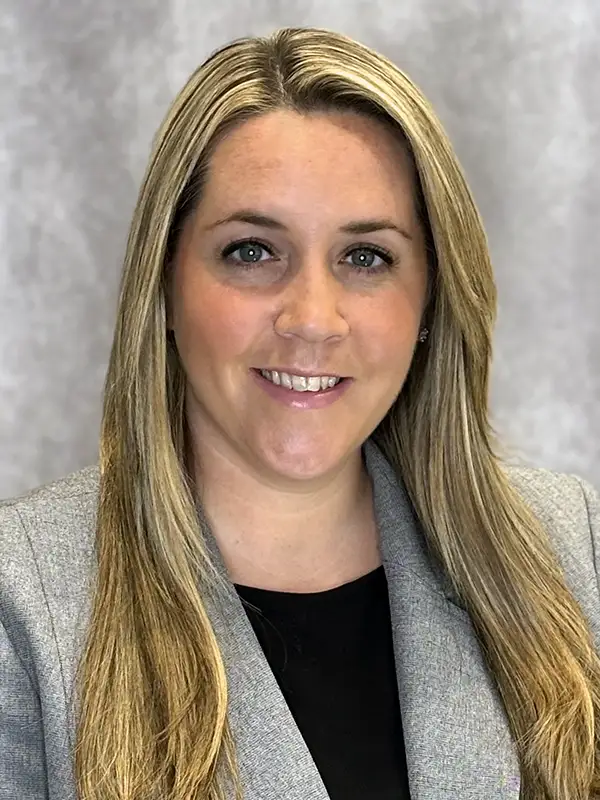
RBT CPA’s Colleen Berry, CPA, Admitted to the Partnership

Colleen Berry, CPA
FOR IMMEDIATE RELEASE

Colleen Berry, CPA

RBT CPAs, LLP takes great pleasure in announcing that Colleen Berry, CPA, of Walden, New York, has been admitted to the firm as a Partner.

Colleen graduated from Marist College in December 2005 with a Bachelor of Science in Accounting. Having interned at RBT’s Newburgh office during tax season of 2005, Colleen officially joined the tax department as an associate in January of 2006. She obtained her CPA in 2011. Colleen is a member of the NYSSCPA’s New York, MultiState, and Local Taxation Committee and currently serves as treasurer for the PTO board of Walden Elementary School. She lives in Walden with her husband, Ray, and their three daughters and enjoys being an active and engaged parent in the local community.

On her new role, Colleen says, “I am honored to become a partner at RBT, and I am grateful for the opportunity to work alongside such a talented, community-minded group of individuals. I look forward to continuing my growth with the firm and contributing to its longstanding commitment to excellence in serving our clients, team members, and community.”

Managing Partner Michael Turturro says, “In her twenty years with RBT, Colleen has proven to be a hands-down talent. Whether she’s tackling a brutal tax season, solving a complex issue, or simply grinding to get things done, Colleen handles it all with grace, incredibly sharp focus, and dedication. We are thrilled to welcome Colleen to the partnership and look forward to seeing her flourish in her new role.”

Living Trust Myths vs. Reality: What a Revocable Trust Really Does

Living Trust Myths vs. Reality: What a Revocable Trust Really Does

Revocable living trusts (RLTs) are common in estate planning, and commonly misunderstood. They’re sometimes presented as a clean, all-purpose solution that avoids probate, reduces taxes, and simplifies everything after death. In reality, they’re more nuanced than that.

This article isn’t meant to argue for or against revocable living trusts. Instead, the goal is to explain what they actually do, what they don’t do, and what’s worth paying attention to if you already have one or are considering setting one up. Like most legal and tax tools, their effectiveness depends heavily on individual facts and circumstances.

What is a revocable living trust?

An RLT is a trust created during an individual’s lifetime that can be amended, restated, or revoked at any time while the grantor (the person who creates it) is alive and competent. In most cases, the grantor also serves as the initial trustee and beneficiary during life – meaning they retain control over the trust and continue to benefit from the assets held in it.

From a practical standpoint, this usually means day-to-day control usually doesn’t change. Assets can still be bought, sold, and managed as before. The trust becomes more relevant if the grantor becomes incapacitated or dies, when a successor trustee steps in to manage or distribute assets under the trust’s terms.

Myth #1: “A revocable living trust automatically avoids probate.”

Reality: Only assets that are actually owned by the trust avoid probate.

Creating the trust document alone isn’t enough. Assets must be properly titled in the name of the trust (often referred to as “funding” the trust). If a home, investment account, or business interest remains in an individual’s name, that asset may still be subject to probate, even if a trust exists.

This is one of the most common disconnects. Many trusts are only partially funded, which can result in a mix of probate and non-probate administration. A revocable trust can help avoid probate, but only for assets that are correctly aligned with it.

It’s also worth noting that probate itself varies widely by state. In some jurisdictions, probate is relatively streamlined and inexpensive. In others, it can be slow, formal, and costly – particularly for real estate. Whether probate avoidance is a meaningful benefit often depends on where the grantor lives and what assets they own.

Myth #2: “A revocable trust reduces estate taxes.”

 Reality: In most cases, it does not.

Because the grantor retains the power to revoke or change the trust, assets held in a revocable living trust are generally still included in the grantor’s taxable estate. From a federal estate tax perspective, ownership hasn’t really shifted.

During life, revocable trusts are usually treated as “grantor trusts” for income tax purposes. Income, deductions, and credits are typically reported on the individual’s personal return, just as they would be if the trust didn’t exist. This treatment is outlined in guidance from the IRS.

That said, while a revocable trust usually doesn’t reduce estate taxes, it may help reduce other estate-related costs. In states where probate is expensive or attorney-intensive, avoiding or minimizing probate can result in lower administrative fees, court costs, and delays. These savings aren’t tax savings, but they can still be meaningful.

Estate tax planning, when needed, generally requires additional strategies beyond a standard revocable trust.

Myth #3: “A revocable trust protects assets from creditors or lawsuits.”

Reality: Generally, it does not – but there are limited, situational benefits worth understanding.

Because the grantor can revoke the trust and reclaim the assets, creditors are usually able to reach trust assets to the same extent they could reach assets owned outright. For this reason, RLTs aren’t considered asset-protection vehicles in the traditional sense.

However, there are narrow circumstances where an RLT can indirectly help preserve assets – not by blocking creditors, but by improving control and administration. For example:

  • Incapacity planning: a well-drafted trust can ensure that a successor trustee steps in seamlessly if the grantor becomes incapacitated, reducing the risk of court-appointed guardianship or mismanagement.
  • Trustee succession safeguards: trust terms can be written to bypass an otherwise-named successor trustee if that person is unable or unsuitable to serve (for example, due to legal financial, or personal issues), allowing an alternate or professional trustee to step in.

These are not creditor-protection strategies in the strict legal sense, but they can matter in preserving assets through orderly management during vulnerable periods.

Myth #4: “Once there’s a trust, beneficiary designations don’t matter.”

Reality: Beneficiary designations often control how assets pass and can override the trust.

Retirement accounts, life insurance policies, and many financial accounts transfer by beneficiary designation. If those designations don’t align with the trust, the trust may not govern those assets at all.

Coordination is key – and it isn’t always intuitive. For example, certain assets, like ordinary bank or brokerage accounts, may be titled in the name of the trust. Others, such as retirement accounts or life insurance policies, are often better left payable directly to individuals, depending on tax, distribution, and planning goals. In some cases, a trust may be named as beneficiary, but only if it’s properly drafted to handle those assets.

There’s no universal rule here. The “right” approach depends on the type of asset, the beneficiaries involved, and the broader estate and tax plan.

Myth #5: “A revocable trust eliminates all court involvement and delays.”

Reality: It can reduce probate involvement, but administration still takes time and effort.

Even without probate, someone must gather assets, pay expenses, handle tax filings, and carry out the terms of the trust. A revocable trust can streamline this process, especially for more complex estates, but it doesn’t eliminate administrative responsibility.

One of the underappreciated benefits of an RLT is that it allows for more detailed and customized instructions than a simple will. This can be particularly helpful when the estate includes a closely held business, multiple properties, or assets that require ongoing management. Clear instructions can reduce uncertainty, minimize disputes, and give successor trustees a practical roadmap during administration.

It changes the process; it doesn’t remove it.

Myth #6: “Revocable trusts guarantee privacy.”

Reality: Privacy is generally the rule, but there are important exceptions.

Unlike probate proceedings, trust documents typically aren’t filed with the court, which helps keep estate details out of the public record. This is one of the most cited advantages of revocable trusts.

However, privacy isn’t absolute. Trustees have disclosure obligations to beneficiaries, and disputes over the trust can lead to litigation. In those cases, certain information may become part of a court record. Even then, trusts are rarely made public in their entirety, but some loss of privacy is possible.

The takeaway: RLTs usually enhance privacy, but they don’t guarantee complete confidentiality in every scenario.

When a revocable living trust can be a good fit

Revocable trusts tend to be most useful when one or more of the following apply:

  • Real estate is owned in more than one state
  • Avoiding probate is a high priority, particularly in states with complex or costly probate systems
  • Continuity is important in the event of incapacity
  • The estate includes complex, illiquid, or hard-to-administer assets
  • Privacy is a meaningful concern
  • Distributions are uneven, long-term, or likely to cause friction among heirs

They can also help reduce the risk of disputes by allowing the grantor to leave clearer, more detailed instructions than would typically appear in a basic will.

In contrast, an RLT may offer limited additional value when an estate is simple, most assets already pass efficiently by beneficiary designation, and state probate rules provide for a streamlined or expedited administration process. Probate varies significantly by state, and in some jurisdictions, the process can be far more burdensome than many people expect.

The most common issue to watch for: trust funding and maintenance

The biggest practical risk with revocable living trusts isn’t the document itself; it’s follow-through.

Assets need to be retitled, beneficiary designations coordinated, and the trust revisited periodically as circumstances change. New accounts, real estate purchases, family changes, or changes in state law can all affect how well the trust works in practice.

The good news is that revocable trusts are flexible. If issues are identified, they can usually be addressed during the grantor’s lifetime through amendments, restatements, or improved coordination.

Practical takeaway 

Revocable living trusts are neither a universal solution nor something to dismiss outright. They’re one tool among many, and their effectiveness depends on how they’re designed, funded, and maintained – and on the individual facts involved.

For those who already have a trust, periodic review can help ensure it still aligns with current goals, assets, and family dynamics. For those considering one, understanding what the trust does – and just as importantly, what it doesn’t do – can prevent surprises later.

If you have questions about how a revocable living trust fits into your broader tax and estate plan, or whether your existing trust is properly aligned with your current circumstances, please contact our office. We’re happy to work with you and your estate planning attorney to ensure asset ownership and tax considerations are coordinated and working as intended.

This article is provided for general informational purposes only and should not be relied upon as legal or tax advice. Estate planning strategies should always be evaluated with qualified professionals in light of your individual facts and state laws.
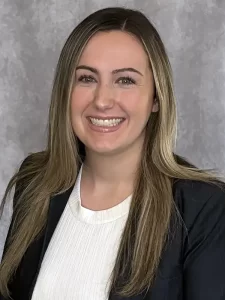
RBT CPA’s Carolyn Bell, CPA, Admitted to the Partnership

FOR IMMEDIATE RELEASE

RBT CPAs LLP takes great pleasure in announcing that Carolyn Bell, CPA, of Arlington, New York, has been admitted to the firm as a partner.

Carolyn graduated from Mount Saint Mary College in 2011, joining RBT’s Client Advisory team in the Newburgh office in 2013 after initially working as an administrative assistant for the firm. Since joining RBT, Carolyn has obtained her CPA and transitioned to the Poughkeepsie office. Carolyn serves as a board member for the Dutchess County Regional Chamber of Commerce and a committee member for the Women’s Leadership Alliance.

Carolyn was born and raised in New Windsor, New York, moving to Arlington in 2020. On becoming partner, she says “Being a trusted advisor to my clients is one of the most rewarding aspects of my career. I truly value each and every one of my client relationships. With our experience, knowledge and incredibly talented team, I look forward to RBT’s continued growth and success.”

Managing Partner, Michael Turturro adds, “We’re thrilled to welcome Carolyn to our partner group. Carolyn is an example of dedication to professional growth as well as commitment to clients. We look forward to seeing her thrive as a partner at RBT.”

RBT CPA’s Nicole Gilmartin, CPA, Admitted to the Partnership

FOR IMMEDIATE RELEASE

Nicole M. Gilmartin, CPA, MBARBT CPAs LLP takes great pleasure in announcing that Nicole Gilmartin, CPA, of Wappingers Falls, New York, has been admitted to the firm as a partner.

Nicole graduated from SUNY New Paltz in 2016 with a Bachelor of Science in Accounting. Nicole began at RBT as an intern, joining the Client Advisory team after graduation. Since joining RBT, Nicole has obtained her CPA and earned an MBA in Public Accountancy from SUNY New Paltz.

Nicole is passionate about engaging with her local community. She serves on a number of local committees including The Chamber Foundation Professional Development Programming Committee, the Hudson Valley Young Professionals Professional Development and Education Committee, the New York State Society of CPA’s Next Gen Committee, and the Angels of Light Angels of Rock Event Committee. She has also been a mentor for the Leadership Dutchess program ever since graduating from the program in 2020.

Nicole’s passion for community service started seven years ago when she first became involved with United Way of the Dutchess-Orange Region. Nicole has volunteered with United Way since that time, serving as the Employee Campaign Manager for the workplace campaign at RBT CPAs, a member of the Emerging Leaders Committee, and a member of the Women United Planning Committee.

Nicole is a lifelong resident of Dutchess County, New York. On her new role as partner, she says “I am excited to become a partner at RBT, where the values of high-quality service, strong relationships, and a deep commitment to the community align with my own. I look forward to growing alongside my team and clients and building lasting relationships.”

Managing Partner, Michael Turturro adds, “Nicole is a very welcome addition to our partner group. Nicole has been an integral member of our Client Advisory team, bringing with her a commitment to quality service and a passion for supporting the local community. We congratulate her on her new role as partner at RBT and look forward to all the amazing work she will do.”

RBT CPAs, LLP has offices located at 11 Racquet Road, Newburgh, NY; 2678 South Road Suite 101, Poughkeepsie, NY; 51 Sullivan Street PO Box 209, Wurtsboro, NY; 590 Madison Avenue 21st Floor, New York, NY; Lake Katrine 2215 Route 9W, Lake Katrine, NY; and Hudson 4071 Route 9, Hudson, NY. We provide accounting, auditing, tax, and business consulting services to clients in the greater Hudson Valley, as well as in other areas of New York State, Connecticut, and New Jersey.

What to Know about Rental Assistance Demonstration (RAD) Conversions

What to Know about Rental Assistance Demonstration (RAD) Conversions

One way Public Housing Authorities (PHAs) address living conditions in properties is via a Rental Assistance Demonstration (RAD) conversion. This changes how a rent subsidy is delivered to a property, while allowing owners to access additional capital. Residents have the same benefits, rights, and protections. However, the process of transitioning from traditional public housing to RAD involves several complexities that PHAs need to understand.

  1. Understanding RAD Conversions: RAD allows PHAs to access additional funding sources for the purpose of maintaining, repairing and/or replacing public housing properties. As a result, affordable housing stock can be improved and preserved. Under this program, public housing properties are converted to the Section 8 program to ensure they remain affordable on a permanent basis.
  2. Benefits of RAD Conversions: Conversion to RAD can provide several benefits. These include access to private sources of capital to make critical repairs and improvements, a stable and predictable funding source, and a reduction in the regulatory and administrative burdens of public housing.
  3. The Conversion Process: The RAD conversion process is complex and involves multiple stages. PHAs must inform residents, hold at least two resident meetings at multiple stages, apply to HUD for approval, complete a physical conditions assessment, develop a financing plan, secure commitments from private or public lenders, and then convert the units (plus temporarily relocate residents, if necessary).
  4. Role of an Accountant: An accountant can play a critical role in guiding a PHA through a RAD conversion. They can help in preparing the financial projections required for the application, reviewing the financing plan, and ensuring compliance with the financial reporting requirements of the Section 8 program.
  5. Risk Management: While RAD conversions offer numerous benefits, they also present some risks. These might include potential displacement of residents during renovations, changes in tenant rent contributions, and possible non-compliance with HUD regulations. PHAs need to carefully consider these risks and develop appropriate risk management strategies.
  6. Resident Engagement: Resident engagement is a critical aspect of RAD conversions. Before submitting a RAD application, PHAs are required to inform and consult with residents (including the Resident Advisory Board). This includes notifying residents about the proposed conversion, holding at least two meetings with residents to discuss the plan and solicit feedback, and providing regular updates on the progress of the conversion. After receiving a Commitment to enter into a Housing Assistance Payment (CHAP) contract, the PHA must have at least two additional resident meetings to share updates and get feedback.

Understanding RAD conversions can be challenging. However, with the right information and guidance, PHAs can successfully navigate this process to improve the quality and sustainability of their housing stock. It is essential for PHAs to collaborate with experienced professionals in the field, such as accountants, to ensure a smooth and compliant conversion process. To learn more, refer to the HUD RAD Resident Fact Sheet.

If you are interested in learning more or getting started with your RAD conversion, RBT CPA accounting professionals are available to help. (We can also support your tax, audit, and advisory needs). To learn more, give us a call today.


RBT CPAs is proud to say 100% of its work is prepared in America. Our company does not offshore work, so you always know who is handling your confidential financial data.

Measuring Success: A Refresher on Key Performance Indicators

Measuring Success: A Refresher on Key Performance Indicators

Do you ever look at certain companies, whether global sensations or local favorites, and wonder – what is it that makes them such strong front-runners in competitive environments? Imagine the potential impact on local businesses and local economies if we could figure that out. After all, strong local businesses build strong local economies, and that benefits everyone.

Of course, there’s a myriad of factors that contribute to accomplished businesses, from having a compelling value proposition that meets certain needs or desires to brand, strategy, customer service, employee engagement, and more. Still, one of the most fundamental but critical drivers of business success is this: setting, monitoring, and measuring key performance indicators (KPIs).

A KPI measures activity that is critical to successfully compete in the marketplace. It can show when something is working well and should continue, while pointing to potential issues and necessary course corrections to keep a business and its employees focused and on track.

A business may have three or four overall KPIs and require each business function and individual employees to set KPIs as well. This way, all efforts are aligned to drive common goals.

In addition to evaluating critical activity, a KPI must be realistic, specific, and quantifiable. It should highlight areas where increased efficiency/decrease in use of resources can be achieved, and illustrate progress over time.

Implementing and tracking KPIs provides reliable data to streamline decision-making, encourages teamwork by promoting cooperation, and offers clarity for workers in terms of performance expectations. (As an added bonus, they can also help identify seasonal trends.)

Setting a KPI is just the start – the real value comes from regularly checking in to see if progress is being made and having a clear course of action once the results of the KPI are known.

Implementing KPIs can increase your business’ efficiency and production capability. An added benefit, KPIs can generate a positive attitude among team members by letting individuals know how they contribute to a business’ success. Setting, monitoring, and measuring KPIs regularly can reenergize your team and align everyone to work together to achieve the same goals.  For information on KPIs, see our story: “Are You Using the Right KPIs for Your Brewery?”

If you are interested in learning more, RBT CPA advisory services professionals are available to help. (We can also support your tax, audit, and advisory needs). To learn how we can be Remarkably Better Together, give us a call today.


RBT CPAs is proud to say 100% of its work is prepared in America. Our company does not offshore work, so you always know who is handling your confidential financial data.

Local CPA Firm Celebrates 55 Years of Being Remarkably Better Together

Local CPA Firm Celebrates 55 Years of Being Remarkably Better Together

FOR IMMEDIATE RELEASE

It was March 1, 1969. Joe Vanacore, CPA, did the unthinkable at the time. He left the security and reputation of a large accounting firm during tax season to start his own business. With one client, a local restaurant – The Ship Lantern Inn, Vanacore put a stake in the ground to create a different kind of accounting firm based out of a small office in Newburgh, New York. Today, that company – RBT CPAs – celebrates the 55th anniversary of when it first opened its doors for business.

Now, over 150 team members work out of RBT’s five locations throughout the Hudson Valley and in New York City. It has been recognized as a best place to work; a People’s Choice winner for tax preparation, financial planning, workplace innovation, and best overall employer; an Inside Public Accounting Top 200 Firm; and an Accounting Today top 100 firm to work for and top tax firm.

RBT Managing Partner Mike Tuturro attributes the company’s success to three factors: clients, colleagues, and community. He explains, “We value the trust clients place in us to deliver an exceptional experience marked by professionalism and integrity. We never take that for granted and I believe that’s why most people, businesses, and other organizations that become our clients stay our clients.”

In fact, the company’s very first client – The Ship Lantern Inn (multi-year winner of Best of the Hudson Valley and Ulster County Best Restaurant) – is still a client today. Third-generation owner Mike Foglia says, “I was 12 or 13 working in the restaurant when Joe would come by to review our books. He and my grandfather hit it off right away. My grandfather became a mentor to Joe and in turn Joe became a mentor to me. Next year, The Ship Lantern Inn celebrates its 100th anniversary and I can honestly say one of the reasons we’re reaching that milestone is the support and guidance we got from RBT CPAs.  They are accountants who demand accountability. They are always straightforward and honest and stress the importance of doing things the right way. When you have the best, there’s no reason to change.”

Today’s leadership at RBT CPAs demands the same from today’s team members. Mike Tuturro explains, “When it comes to colleagues, we really look for a particular type of person to join our team. They have to be smart go getters who will always go above and beyond to deliver exceptional value and results. They have to be willing to learn from the generation before them and then pass on that knowledge and opportunity to the up-and-coming generation. And they have to have the drive to give back and make a difference in the communities where we live and operate. Have no doubt – it is our people who have made us what we are today and who will carry on our legacy well into the future.”

Mike also notes that many of its team members were born, raised, and educated in surrounding communities and have a vested interest in giving back. Out of respect for its Hudson Valley roots, the company has a firm policy to never send work outside the U.S.A. – a tactic used by many firms today to drive profit margins.

Mike says, “We want our clients to be 100% confident that local RBT CPAs team is doing the work and handling their financial information, from start to finish. Plus, we believe hiring local people and keeping jobs in the communities where we operate is simply the right thing to do.”

Over the years, the firm’s name changed a number of times to reflect new partners resulting from acquisitions and internal promotions. Eventually, when the list of names became too much of a mouthful, they landed on RBT CPAs, stemming from the belief that the firm, clients, colleagues, and local communities are Remarkably Better Together.

Resolve to Strengthen Your Bidding Process in 2024

Resolve to Strengthen Your Bidding Process in 2024

Creating winning project bids is a science onto itself. Do it right and you open up opportunities to maintain or enhance your business’ profitability (pending actual performance on-the-job). The secret is to not forget to invest the time and attention to show the buyer why your business is the best for the job. In truth, that’s easier said than done, but there are ways to promote your chance at success.

Before anything else, consider whether a project is worth bidding on. If a job is simply a stretch, don’t do it. If there’s slim to no chance of winning, take a pass. Invest in bidding on projects that match your capabilities and business goals.

Make sure you completely understand the project scope. Become familiar with all project documents, plans and specifications, including bonding requirements, inspections, and security clearance. Review the request in detail, noting important points like whether you have to be prequalified to bid, the submission deadline, mandatory meetings, and any specific materials required. If you need clarification, ask! Not including all information requested can be an automatic reason for denial.

Research the company requesting the bid and any team members (i.e., architects) to gain insights into their values and priorities, client base, past projects, and more.

Assess risks and define how you plan on mitigating them. Are there any red flags that can cause problems like unknown site conditions, safety concerns, accelerated timelines, or inaccurate bidding documents?

Attend pre-bid meetings and conduct site visits to clarify project requirements and obtain answers to any questions. Are any bonds required? Does the client have participation goals for minority businesses or ESG? Can you substitute materials? Your goal should be to clarify expectations and identify any potential issues (like a work site not being easily accessible).

Define costs, accountabilities (who is responsible for what), and a project timeline. Estimates should encompass labor, mobilization, equipment (including fuel and transportation to/from a work site), and materials. If a job requires subcontractor work, get bids from at least three subcontractors and review closely for competitiveness, completeness, and accuracy. When it comes to accurate takeoffs and measurements, the importance cannot be overstated. Once you have a final bid, consider whether it will prove beneficial for your business. Sometimes not making a bid is the best decision you can make.

If you decide to move ahead with submitting the bid, have someone else proofread it and double-check all of the math. Confirm that all requested paperwork is included.

After submitting your bid, maintain communication with the potential client, subcontractors, and suppliers. Don’t hesitate to reach out to the potential client for periodic updates, especially if the project can impact other bids and work.

Finally, periodically review your bid process. How many projects have you won or lost? For losses, consider reaching out to the client or project manager for feedback. Learn whether there are adjustments you can make – without compromising profitability – to improve your hit rate going forward.

When Business Slows Down, New York’s Shared Work Program Helps You Retain Valued Employees

When Business Slows Down, New York’s Shared Work Program Helps You Retain Valued Employees

Perhaps the only thing harder than finding valued employees these days is having to lay off employees when business slows down. The New York State Department of Labor (NYS DOL) has a long-standing program that gives you an alternative to lay-offs. It’s called The Shared Work Program. Here are some highlights…

Who Is Eligible?

If you have two or more full-time employees in NYS; you have paid into unemployment insurance for at least four consecutive calendar quarters; and participation helps your organization avoid layoffs, you are eligible to apply.

What Is the Shared Work Program?

Rather than lay off valued talent during a slow period, the program allows you to reduce hours across the board for all employees or within a defined workgroup. Employees who are impacted can make up a portion of lost wages due to a reduction in hours via unemployment insurance.

For example, let’s say work is slowing down. Rather than lay off employees in the XYZ department, you file a Shared Work Plan with the NYS DOL and receive approval to reduce XYZ employees’ hours 20% for 10 weeks. Impacted employees can file for Unemployment Insurance and collect 20% of their weekly benefit. (That’s in addition to the reduced pay they receive from you for working the reduced hours.) As a result, the employees have more income than if they were laid off, and you have a valuable way to retain employees.

When should I get the process started?

Reach out to the Shared Work Program less than one month before the proposed start date. You’ll use that time to create a Shared Work Plan and apply for program approval.

Where can I learn more and apply?

For program details – including FAQs, informational videos, a program fact sheet, references from organizations and employees who have benefited from the program, how to apply, and more, click here.

Why does the NYS DOL offer this program?

This win-win program supports organizations during challenging times by helping them retain valued employees. At the same time, it helps employees stay employed and make up a portion of wages lost due to a reduction in hours.

How?

Develop a Shared Work plan and then apply online. You’ll be assigned a dedicated representative to help guide you. Approvals are granted within 48 hours and can be adjusted weekly. Once business picks up, you can quickly resume normal operations with the same employees you have come to count on…and who knows they can count on you.


We hope this reminder proves useful. Please know you can always count on RBT CPAs for all your accounting, tax, audit, and advisory needs. To learn more, give us a call today. RBT CPAs does not outsource work to any other country. All of our work is prepared in the U.S.A. 

Our Thoughts on the IRS’s $80 Billion Plan

Our Thoughts on the IRS’s $80 Billion Plan

Since April 6, the Internal Revenue Service’s (IRS’s) $80 billion plan – funded under the Inflation Reduction Act (IRA) – has fueled a lot of analysis and speculation among media sources, industry groups, political parties, and American taxpayers in general.

While numerous resources sharing their opinions cater to certain demographics and affiliations, only time will tell whose interpretation is most accurate (or whether they are all accurate in some way). In the meantime, we at RBT CPAs have taken a detailed look at the plan, as well as thoughts from other sources. Following is our initial take on what is sure to be the topic of many office and dinner discussions in the days ahead.

To start with the basics, the plan defines five key objectives, which will be achieved through 42 key initiatives with over 190 programs and 200 milestones between 2023 and 2031:

  1. Dramatically improve services to help taxpayers meet their obligations and receive the tax incentives for which they are eligible
  2. Quickly resolve taxpayer issues
  3. Expand enforcement on taxpayers with complex tax filings and high dollar noncompliance
  4. Operate more effectively using innovative technology, data, and analytics
  5. Attract, retain, and empower a highly skilled, diverse workforce and culture

Based on these objectives alone, we think it is fair to say the plan is comprehensive and addresses the critical components required to transform the agency and bring it into the 21st century. Upon a closer look at the plan, some additional observations began to emerge:

There is going to be more to the story.

The first page indicates the plan covers 2023 to 2031. Yet, most of the milestones outlined in the plan appear to be accomplished by 2025 and 2026. While we agree it is strategic to reassess and refine plans along the way, we do believe this opens the door for a sequel to the plan in a few years, and there is no telling how the story will play out.

The main goal is hiding in plain sight.

Although there is a lot of emphasis on service, technology upgrades, and building a skilled workforce and the right culture, it is striking how often the plan references and returns to enforcement. When you look purely at the financial investment and timeline, it is clear the biggest priority is to address the “tax gap.” Over half the planned investment targets enforcement. Most of the milestones for enforcement show progress being driven by 2025. Even the mission statement published at the start of the plan seems to make clear what’s the top priority: “Provide America’s taxpayers top-quality service by helping them understand and meet their tax responsibilities and enforce the law with integrity and fairness to all.”

Even with multiple references to the enforcement focus being on high income and high wealth individuals, partnerships and corporations, we can’t help but notice the four words that follow the discussion on how this will impact those making under $400,000 annually: “All efforts will comply with your directive not to use IRA resources to raise audit rates on small businesses and households making under $400,000 per year, relative to historic levels.” So, while there is no doubt enforcement will primarily target high income earners, the same percentage of lower earners audited today will continue to be audited in the future. The enhanced workforce and technology capabilities, we speculate, may result in audits garnering more income for the IRS than in the past.

We do not know how far back the new-and-improved IRS will reach in terms of enforcement.

As noted on the IRS webpage on audits, “Generally, the IRS can include returns filed within the last three years in an audit. If we identify a substantial error, we may add additional years. We usually do not go back more than the last six years. The IRS tries to audit tax returns as soon as possible after they are filed. Accordingly, most audits will be of returns filed within the last two years.” We only mention this because it goes hand in hand with our prior point: with more enforcement, not only will there be more audits, but each one may be more fruitful for the IRS than what they are now.

There are three key “ifs” that may impact the plan’s execution.

First, each program in the plan highlights numerous co-dependencies or contingencies – meaning all the stars will have to align for this to be executed as planned.

Second, there are a number of references to the importance of annual IRS funding and increases for inflation. Should this not occur, funding for the plan – and its impact – may erode. (See Commissioner Werfel’s cover memorandum stating: “To cover steady state operations, annual discretionary appropriations must be fully maintained at the FY 2022 level, including growth for inflation and pay raises. Any reduction in annual discretionary funds – including not providing for inflationary increases to maintain current levels – will require IRA funding to be shifted to general operations.”)

And third, the plan relies on a significant uptick in all types of staffing at the same time the talent pool is shrinking and competition to attract and retain highly skilled talent – including accountants and technology specialists – is fierce.

Everyone will be impacted by the plan.

Page 132 of the plan defines stakeholders. It says: “Within this Plan, taxpayers are referred to broadly and include all people and groups whom we serve, including: • Individuals and families • Businesses large and small • Charities and other tax-exempt organizations • International taxpayers • Federal, state, and local governments • Tribal nations • Tax professionals and others who assist and serve taxpayers.” Translation: While there will be a lot of focus on high earning, wealthy individuals and institutions, everyone is going to feel the impact somehow. Exactly how remains to be seen.

One other thought:

While some are still calling for the IRS to reallocate the budget so there’s equal emphasis on service, technology and enforcement, the fact is the IRS does not have the discretion to change how funds are allocated. Still, with groups like the American Institute of Certified Public Accountants calling for a more equitable allocation of funds, you never know…


This story will be continued in the days, months and years ahead. We will be sure to keep you updated and share our thoughts as things unfold. If in the meantime, you have any questions or need accounting, tax, auditing, or advisory services, RBT CPAs is here for you. Just give us a call. NOTE: This alert shares RBT CPAs’ initial interpretations. It should not be construed as legal or financial advice or direction.